Short answer: A hail damage claim in Oklahoma usually goes like this: document the damage, protect the house from further harm, get a roof inspection and written estimate, call your insurance company, meet the adjuster, review the payment, and then repair the roof. Your policy sets the rules, including your deductible, so read it before you call.
If a storm just rolled through Broken Arrow, Tulsa, Bixby or Jenks, you’re probably staring at a roof and wondering where to start. Here is the process in plain English.
What is the first thing to do after hail hits my roof?
Take pictures. Walk around the outside of your house and photograph or video anything that looks damaged: dented gutters, damaged vents, dings on the siding, shingles with bare spots or cracked mats, and hail marks on the yard and your car. Take wide shots and close-ups. If water is coming in, photograph the ceiling stains too.
The Oklahoma Insurance Department’s advice is not to throw anything away unless your insurance company tells you to. Keep damaged pieces if you can.
Do I need to make repairs right away?
You need to stop more damage from happening, but you should hold off on permanent repairs. The Oklahoma Insurance Department says to cover holes, broken windows and leaking roofs to prevent further damage, and to wait on permanent repairs until your insurance company has inspected and you’ve agreed on the cost of repairs.
A tarp or temporary patch is fine. Keep every receipt. Some policies reimburse reasonable temporary repair costs, so ask your insurer.
How do I know if I should file a claim at all?
Have a roofer look at it first. The Oklahoma Insurance Department suggests having your roof inspected by a trusted contractor. If the damage is below or only slightly above your deductible, you may be better off paying for the repair yourself. If it substantially exceeds your deductible, that’s when you turn in a claim.
That’s why your deductible matters. Many Oklahoma homeowners policies have a separate wind and hail deductible, and it is often a percentage of your home’s insured value instead of a flat dollar amount. Look at your policy’s declarations page to see yours. We’d rather tell you honestly that your roof doesn’t need a claim than send you into one that doesn’t make sense. Hail damage is also not always covered the same way on every policy, because some include limits such as exclusions for cosmetic-only damage.
What happens at a roof inspection?
A roofer climbs up and looks for the kinds of damage that matter: fractured or bruised shingles, granule loss that exposes the mat, damaged flashing, vents, and ridge caps, and problems with the gutters and downspouts. At Shingle RX of Oklahoma, a free roof inspection means we look at your roof, take photos, and tell you straight what we see, even when the answer is “you’re fine for now.”
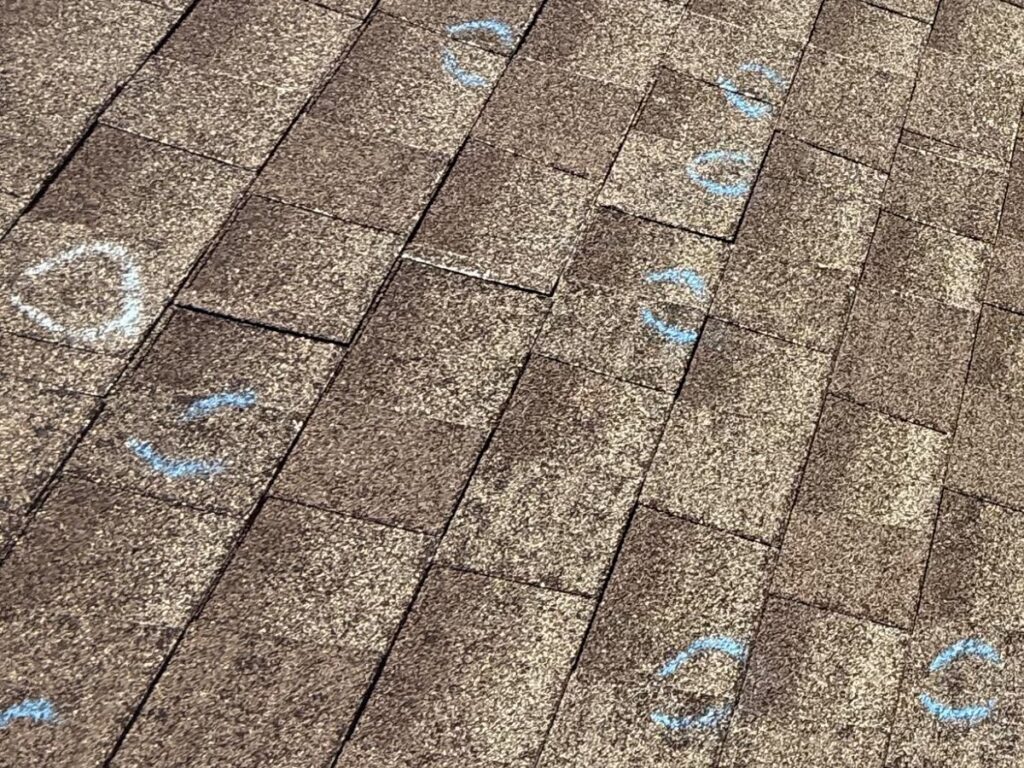
Chalk circles mark the hail hits an inspector finds, so the damage is easy to see and photograph.
If there is storm damage, we can give you a written repair or replacement estimate, which you are free to send to your insurance company.
How do I file the claim?
Call your insurance company or agent, tell them about the storm date and what you found, and ask what forms, documents and information they need. The Oklahoma Insurance Department suggests contacting your insurer after you have an estimate for repairs. Many policies have a deadline for reporting a loss, so don’t wait around. Read your policy or ask your agent what yours is.
Write down your claim number, the name of the person you spoke with, and the date.
What happens when the adjuster comes out?
The insurance company sends an adjuster to inspect the damage and write up their own estimate of the loss. You’re allowed to be there, and your roofer can be there too to point out damage and answer the adjuster’s questions about the estimate.
We walk homeowners through what we find on their roof.
One important thing about Oklahoma rules: a roofing contractor cannot negotiate your claim for you or act as your representative with the insurance company. That is the job of a licensed public adjuster, and the Oklahoma Insurance Department has said contractors shouldn’t take on that role. Be careful with any roofer who says they will “handle your claim” or “deal with the insurance company” for you. A good contractor inspects, documents, estimates, and does the repair. The claim itself stays between you and your insurer.
Will the roofer pay my deductible?
No, and nobody should offer to. Oklahoma law says a roofing contractor can’t advertise or promise to pay all or part of your insurance deductible, or offer to compensate you for providing a service, as an inducement to get the job. If a contractor breaks that rule, the insurance company doesn’t have to consider that contractor’s estimate. Oklahoma roofers are also required to give you written notice of this rule with their initial estimate.
So if someone knocks on your door in Owasso or Sapulpa after a storm and says “we’ll cover your deductible,” that’s your cue to say no thanks.
How does the insurance payment work?
Payments depend on your policy. With a replacement cost policy, insurers often pay part of the money up front and release the rest after the work is done. With an actual cash value policy, the payment accounts for depreciation. The Oklahoma Insurance Department notes that replacement cost policies can require work to be finished within a set window to receive the withheld payments, and cites six months from the date of loss. Your policy may differ, so confirm the exact time limit with your insurer.
Don’t sign over your insurance check to a contractor, and don’t pay the full amount up front. The Oklahoma Insurance Department recommends paying in installments as work is completed.
What if I disagree with the adjuster’s estimate?
You can ask your insurance company to review it. Send them your contractor’s written estimate and photos, and ask them to explain any difference line by line. If you’re still stuck, you can contact the Oklahoma Insurance Department’s consumer assistance line, or talk to a licensed public adjuster or an attorney who works on insurance claims. We can’t give legal advice or negotiate for you, but we can give you a clear, written estimate that shows what your roof needs.
Frequently asked questions
Does homeowners insurance cover hail damage in Oklahoma?
Most standard homeowners policies cover hail damage to the roof, according to the Oklahoma Insurance Department, but policies can include restrictions like higher hail deductibles or cosmetic damage exclusions. Check your policy or ask your agent.
Should I get more than one estimate?
Yes. The Oklahoma Insurance Department recommends getting more than one bid, checking references, and never signing a contract with blank spaces.
Will filing a hail claim cancel my policy?
We can’t speak for your insurance company, so ask your agent how claims affect your policy and rates before you file.
How long will the repair take?
It depends on the roof size, weather and material delivery. After a big storm, local roofers get busy, so schedules can stretch. Ask for a realistic start date in writing.
Can a roofer file the claim for me?
A roofer can recommend that you file, give you an estimate, and be at the inspection, but the claim is yours to file and manage.
What does Shingle RX of Oklahoma do for storm-damaged roofs?
We inspect roofs across the Tulsa metro, give honest written estimates, and handle repairs and replacements. If your shingles are worn but still structurally sound, we’ll also tell you about shingle rejuvenation as an option.
Want someone to look at your roof?
Shingle RX of Oklahoma is based at 1920 W Albany St in Broken Arrow and serves homeowners in Tulsa, Bixby, Jenks, Owasso, Sand Springs, Sapulpa, Glenpool, Coweta, Skiatook, Collinsville and nearby towns. We have a 4.8 rating on Google from about 177 reviews, and we’d be glad to take a look at your roof for free. Call us at (844) 777-2979 or request a free inspection.